
Marriage doesn’t combine two credit histories into one. Credit repair for married couples starts with understanding each spouse’s individual reports, then addressing inaccurate or outdated information on the file where it appears. If an item is disputed, credit bureaus have 30 days to review and respond, according to the Consumer Financial Protection Bureau. That review period can begin a correction process, but it doesn’t make every credit concern a 30-day fix.
It’s understandable to want a clear timeline, especially when a joint loan or shared financial goal is approaching. Start by understanding how each spouse’s accounts, payment history, and credit applications affect your plans. This guide explains how disputes work, when separate or joint accounts may help, and what to consider before co-signing. It also covers how credit-repair services differ and which cost factors to weigh, so you can make a more informed decision.
Key Takeaways
- Start by understanding that each spouse has an individual credit history, then identify which report items may need attention.
- Weigh the responsibility that comes with co-signing, including how missed payments could affect both spouses.
- Compare separate, joint, and authorized-user accounts based on whose credit file receives the activity and who shares the risk.
- Assess credit-repair services by the work and level of support included, not just by the way a plan is priced.
1. How Does Credit Repair for Couples Work?
Marriage doesn’t merge two credit histories into one. Each spouse has an independent credit file, and an account usually appears on the report associated with its owner or borrower. Credit repair for married couples therefore starts with reviewing both spouses’ credit reports, rather than treating household credit as a single score. Differences between partners’ scores may reflect their distinct payment histories, accounts, and reported information.
Review reports from all three U.S. credit reporting agencies for each spouse. Compare the accounts, balances, payment records, and inquiries on each report. Look for errors, such as a late payment that was made on time, an account that doesn’t belong to that spouse, or an inaccurate balance. Note which spouse’s report contains each item, then gather relevant account statements or payment records to support a dispute.
Negative information can remain for years, even when a couple is working toward better credit. According to the Consumer Financial Protection Bureau, late-payment marks can remain on a credit report for 7 years. A Chapter 7 bankruptcy remains on each affected spouse’s credit report for 10 years, while a Chapter 13 bankruptcy remains for 7 years, according to the Consumer Financial Protection Bureau. The Consumer Financial Protection Bureau also says negative credit-report items typically remain for seven years from the original delinquency date. Removing inaccurate information is different from removing accurate history that is still reportable.
For an inaccurate item, dispute the specific entry with the credit bureau and identify why it’s wrong. Under the Fair Credit Reporting Act, credit bureaus have 30 days to review and respond to a disputed credit report item, according to the Consumer Financial Protection Bureau. Track the dispute and its response for the spouse whose file contains the item. One spouse’s correction doesn’t automatically change the other’s report.
Warning signs include promises to erase accurate negative information or guarantee a particular score. The key rule here is the bureau’s 30-day review period for a disputed item; a company’s promise doesn’t replace checking the evidence, the item’s accuracy, and the written dispute outcome.
2. Co-signing risks and release options
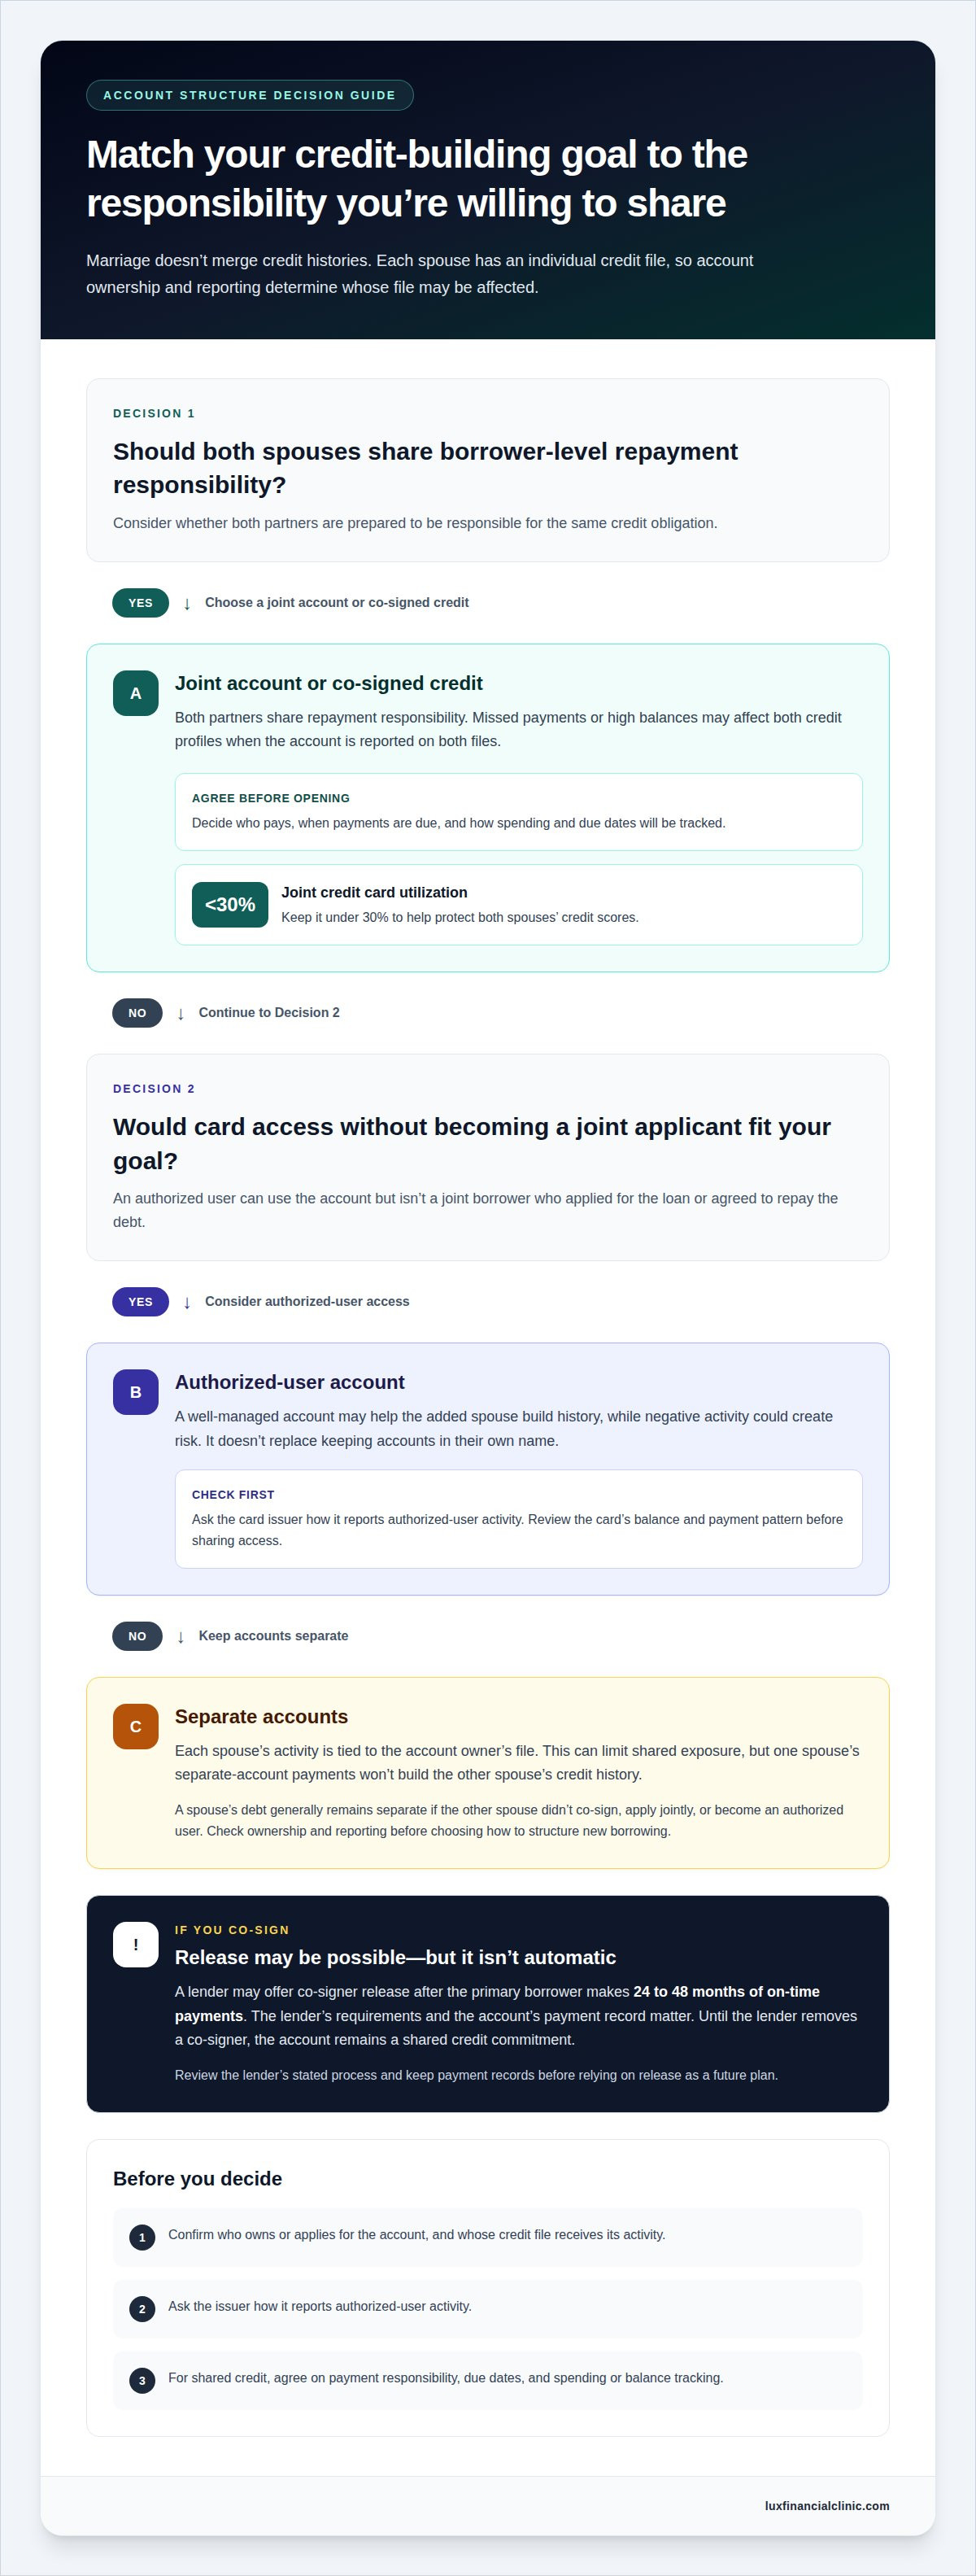
Co-signing can help a spouse qualify for a credit card or loan, but it also makes both partners responsible for repayment. If the primary borrower misses payments, the account’s negative history may affect both credit scores if it’s reported on both files. A high balance may also affect the credit profiles linked to the account. Before signing, agree on who pays, how you’ll track due dates, and how you’ll respond if household income changes.
An authorized user has a different role from a co-signer. An authorized user can use the account, but isn’t a joint borrower who applied for the loan or agreed to repay the debt. Ask the card issuer how it reports authorized-user activity, then consider whether sharing access fits your budget and goals. With a co-signed credit card, both partners share repayment responsibility, so missed payments or growing balances may affect both.
Release options depend on the lender and account terms. Co-signer release may be available after the primary borrower makes 24 to 48 months of on-time payments. That isn’t automatic: the lender’s release requirements and the account’s payment record matter. Keep payment records and review the lender’s stated process before relying on release as a future plan. Until the lender removes a co-signer, the account remains a shared credit commitment.
Divorce doesn’t, by itself, settle who must pay a co-signed debt or remove a name from the account. A separation agreement between spouses may not change the lender’s account terms. If one spouse keeps using a shared credit card, discuss spending limits, payment responsibilities, and a plan for closing or separating the account with the lender. If negative items are influencing this decision, credit repair support can help clarify the credit issues before you take on shared borrowing.
3. Separate or joint accounts: which builds credit faster?
With separate accounts, each spouse’s credit activity is tied to the account owner’s file. A spouse’s debt generally remains separate if the other spouse didn’t co-sign, apply jointly, or become an authorized user. This can limit shared exposure, but payments on one spouse’s separate account won’t build the other spouse’s history. Review account ownership and reporting before deciding how to structure new borrowing.
A joint account connects both spouses to the same credit obligation. On a joint credit card, both partners should agree on who pays, when payments are due, and how spending is tracked. Keep joint credit utilization under 30% to help protect both spouses’ credit scores. If one spouse has stronger credit standing, sharing an account may help the other build history, but missed payments or high balances can affect both.
An authorized-user account is another option: one spouse is added to the other’s credit card without becoming a joint applicant. Before adding a spouse, ask the issuer how it reports authorized-user activity and review the card’s balance and payment pattern. A well-managed account may help, while negative activity could create risk. It doesn’t replace the added spouse’s need to maintain accounts in their own name.
Collection accounts need a separate approach. Before negotiating payment or removal, request debt validation and review whether the collection details are accurate. If an entry is inaccurate, dispute the specific information with the reporting bureau or the company that furnished it. Negotiating a balance doesn’t mean the collection will be removed, so get any agreed reporting terms in writing before paying. For example, a couple can address an inaccurate collection on one spouse’s file without assuming it appears on the other’s reports. This keeps the next step focused on the account and person actually affected.
4. Credit repair pricing and services for couples
When comparing credit-repair services, first distinguish the work from the billing model. One spouse may need help addressing inaccurate collections, while the other may need support reviewing a broader credit history. A shared household goal doesn’t mean both files require the same work. Compare what each service includes, which reports it addresses, and how it communicates progress and next steps.
Some services charge monthly, while others may use setup charges or package-based fees. The price depends on the case and is given after a quote request; relevant factors include the number and type of disputed items, the reports involved, and the level of ongoing support. For example, a couple with one inaccurate entry on one spouse’s report may need a different scope from partners addressing several complex items across both files.
Ask what the service does before comparing costs. Useful details include whether it reviews each partner’s reports, prepares disputes about inaccurate information, tracks bureau responses, and explains what happens next. Also clarify how billing works if a dispute remains unresolved or accurate negative information cannot be removed. A clear scope helps partners avoid duplicate work on the same account and understand which spouse’s file is being addressed.
Credit-repair services can challenge inaccurate information, but paying a collection doesn’t automatically mean it will be removed. A service also can’t control how a bureau responds or promise a particular score. Compare the work offered with your household’s needs, and keep paying current obligations while disputed items are reviewed. This helps couples assess the value of a service without mistaking a fee for a guaranteed outcome.
For a practical comparison, write down each spouse’s main credit concerns, the services proposed for each report, and the billing arrangement. Then consider whether ongoing guidance fits your relationship’s goals or whether focused help with specific inaccuracies is more appropriate. Explore credit-repair support options to identify a service aligned with the work your household needs.
Lux Financial Clinic
Lux Financial Clinic helps couples clarify credit concerns affecting one or both spouses. Its credit repair services use structured dispute protocols to address inaccurate negative items, including collections, charge-offs, and late payments. A Financial Diagnostic Consultation can help clarify the issues and identify a suitable next step.
Depending on the work needed, couples can consider the Credit Repair - Basic/Repair Package or Credit Repair - Comprehensive/Build Package. The focus is on challenging inaccurate credit information, not promising a particular score or removing accurate history. These packages can help partners address separate credit files in a more organized way while keeping shared financial goals in view.
To discuss your credit concerns and identify a suitable next step, contact Lux Financial Clinic.
Set a shared direction for your next financial step
A constructive next step is to agree on what financial progress means for your household. You might be preparing for a major purchase, strengthening each spouse’s credit profile, or organizing finances around a business goal. A shared plan can help you make clearer decisions while keeping each partner’s individual needs in view.
For credit support, Lux Financial Clinic offers the Credit Repair - Basic/Repair Package and Credit Repair - Comprehensive/Build Package. Couples with business-related goals can also explore Business Funding Consulting. The right direction depends on the work you want addressed and your shared financial priorities. Credit repair for married couples can be part of a broader effort to build a more intentional financial foundation together.
When you’re ready to discuss your goals and possible next steps, contact Lux Financial Clinic today. A clear conversation can help you move forward with greater confidence and a plan that reflects both partners’ priorities.
Frequently Asked Questions
How Can I Fix My Credit Score in 30 Days?
You can use 30 days to address errors and strengthen current habits, but a particular score change can’t be promised. Prioritize correcting inaccurate information, paying bills on time, and avoiding unnecessary new credit applications. For example, if an account shows a payment as late despite a timely payment, collect the relevant proof and dispute that specific entry. Accurate negative history may take longer to change.
How Does Credit Repair for Couples Work?
Credit repair for couples means addressing each spouse’s credit concerns separately while coordinating household decisions. For example, one partner might need to correct an account that isn’t theirs, while the other focuses on managing current card balances. Keep a shared record of goals and agreed responsibilities, but tie each dispute or account action to the spouse whose credit file it concerns.
How does your spouse's credit affect yours?
Your spouse’s credit history generally doesn’t become part of yours just because you’re married. Their credit can matter when you borrow together, however, and accounts you hold jointly may affect both partners. Before applying together, consider how each person’s credit standing and existing obligations fit the planned payment. A spouse’s separate account doesn’t automatically become your account.
Separate or joint accounts: which builds credit faster?
Neither structure builds credit faster in every situation. Separate accounts let each spouse establish a record through their own activity, while joint accounts connect both partners to shared borrowing. For instance, a spouse with limited account history may benefit from responsible shared activity, while separate accounts can preserve individual financial independence. Choose based on payment reliability, account terms, and each partner’s ability to manage the commitment.
Should you add your spouse as an authorized user?
Consider adding a spouse only after reviewing the card’s payment history, balance, and issuer reporting. An authorized-user account gives a spouse access to the card, but its effect on their credit depends partly on whether the issuer reports the account for them. Discuss spending boundaries first. If the primary cardholder carries a high balance or misses payments, adding a spouse may create unwanted credit concerns.
What If One Spouse Has Been Hiding Credit Problems?
Start with a calm conversation about current household obligations and immediate priorities, not blame. Set aside time to review shared bills, accounts, and upcoming payments, then agree on who will handle each responsibility. Hold off on new shared borrowing until both partners understand the situation. If talking feels difficult, a neutral Financial Diagnostic Consultation can help organize the next steps.


