
Preparing for business financing starts with understanding your credit, not simply applying for a loan. Credit repair and funding consulting address different parts of that process: credit repair focuses on potentially inaccurate information in your credit reports, while funding consulting helps you organize a financing strategy around your business needs and goals.
This guide explains how the services can work together, what each can realistically do, and how to choose a practical starting point. You’ll learn how credit repair differs from credit building, what funding guidance can involve, and why no service can promise a particular score, approval, funding amount, or financing terms.
A focused diagnostic conversation can help you move from reviewing your credit to organizing next steps. We’ll cover the distinctions, how credit preparation relates to funding strategy, and what to bring to a tailored consultation.
Key Takeaways
- Credit repair focuses on reviewing and disputing potentially inaccurate or unverifiable report information; funding consulting helps organize a business financing strategy.
- Credit repair and funding consulting can support different parts of your preparation, and their steps may follow separate timelines.
- Choose a starting point based on your current need: review questionable credit report items, clarify funding goals, or address both.
- Prepare for a diagnostic conversation by gathering current credit reports, key business details, and a clear description of your funding goal.
- Lux Financial Clinic offers basic and comprehensive credit repair packages, along with funding guidance tailored to your business needs.
What Credit Repair and Funding Consulting Each Do for a Business Owner
If you’re preparing to seek business capital and want a clearer view of your credit, start by separating two related but distinct services. Credit repair focuses on the accuracy of information in your credit reports. Funding consulting helps you consider funding paths and prepare to approach potential lenders.
Neither service can guarantee a score change, loan approval, funding amount, or financing terms. Their value is in helping you understand your starting point, address relevant concerns, and make informed decisions about what to do next.
What credit repair can and cannot address
Credit repair involves reviewing credit reports and disputing information that may be inaccurate or unverifiable. The review can include collections, charge-offs, late payments, and hard inquiries. For example, if an account is unfamiliar or a reported payment history conflicts with your records, dispute support can help bring the specific concern forward for review.
Accurate, current negative information is not promised to be removed. Disputing report items is also different from building positive credit habits over time. Consistent payment practices and thoughtful credit use may support credit building, but a dispute has a narrower purpose: to address information that may be wrong or cannot be verified.
What funding consulting contributes
Funding consulting focuses on your business’s financing needs and possible routes to explore. Guidance can cover funding opportunities, loans, credit lines, and lender introductions. A consultant can help you consider how a capital need fits your business plans and prepare to approach potential lenders. The lender makes its own decisions about underwriting, approval, amounts, and terms.
This distinction matters: a consultant provides guidance, not a loan or underwriting decision. Business funding decisions also involve broader questions about how a company manages capital and funding sources. The Corporate Finance Overview offers foundational context on that subject.
Credit repair and funding consulting can be useful together, but they don’t need to happen in lockstep. Reviewing potentially inaccurate items may follow a different course from organizing business information or exploring funding options. Treating these as separate tracks helps set realistic expectations and avoids assuming a credit dispute guarantees financing readiness.
For a broader look at preparation, explore this credit readiness for business funding guide. It explains how credit review can fit into a wider funding conversation and help you consider next steps in light of your circumstances and business goals.
How Credit Repair and Funding Consulting Can Work Together
Once you understand the separate roles of credit review and funding guidance, coordinate them around your business goal. You can address report information that needs attention while organizing the details a lender may consider. The aim is clearer preparation, not a promise that any one step will determine the outcome of an application.
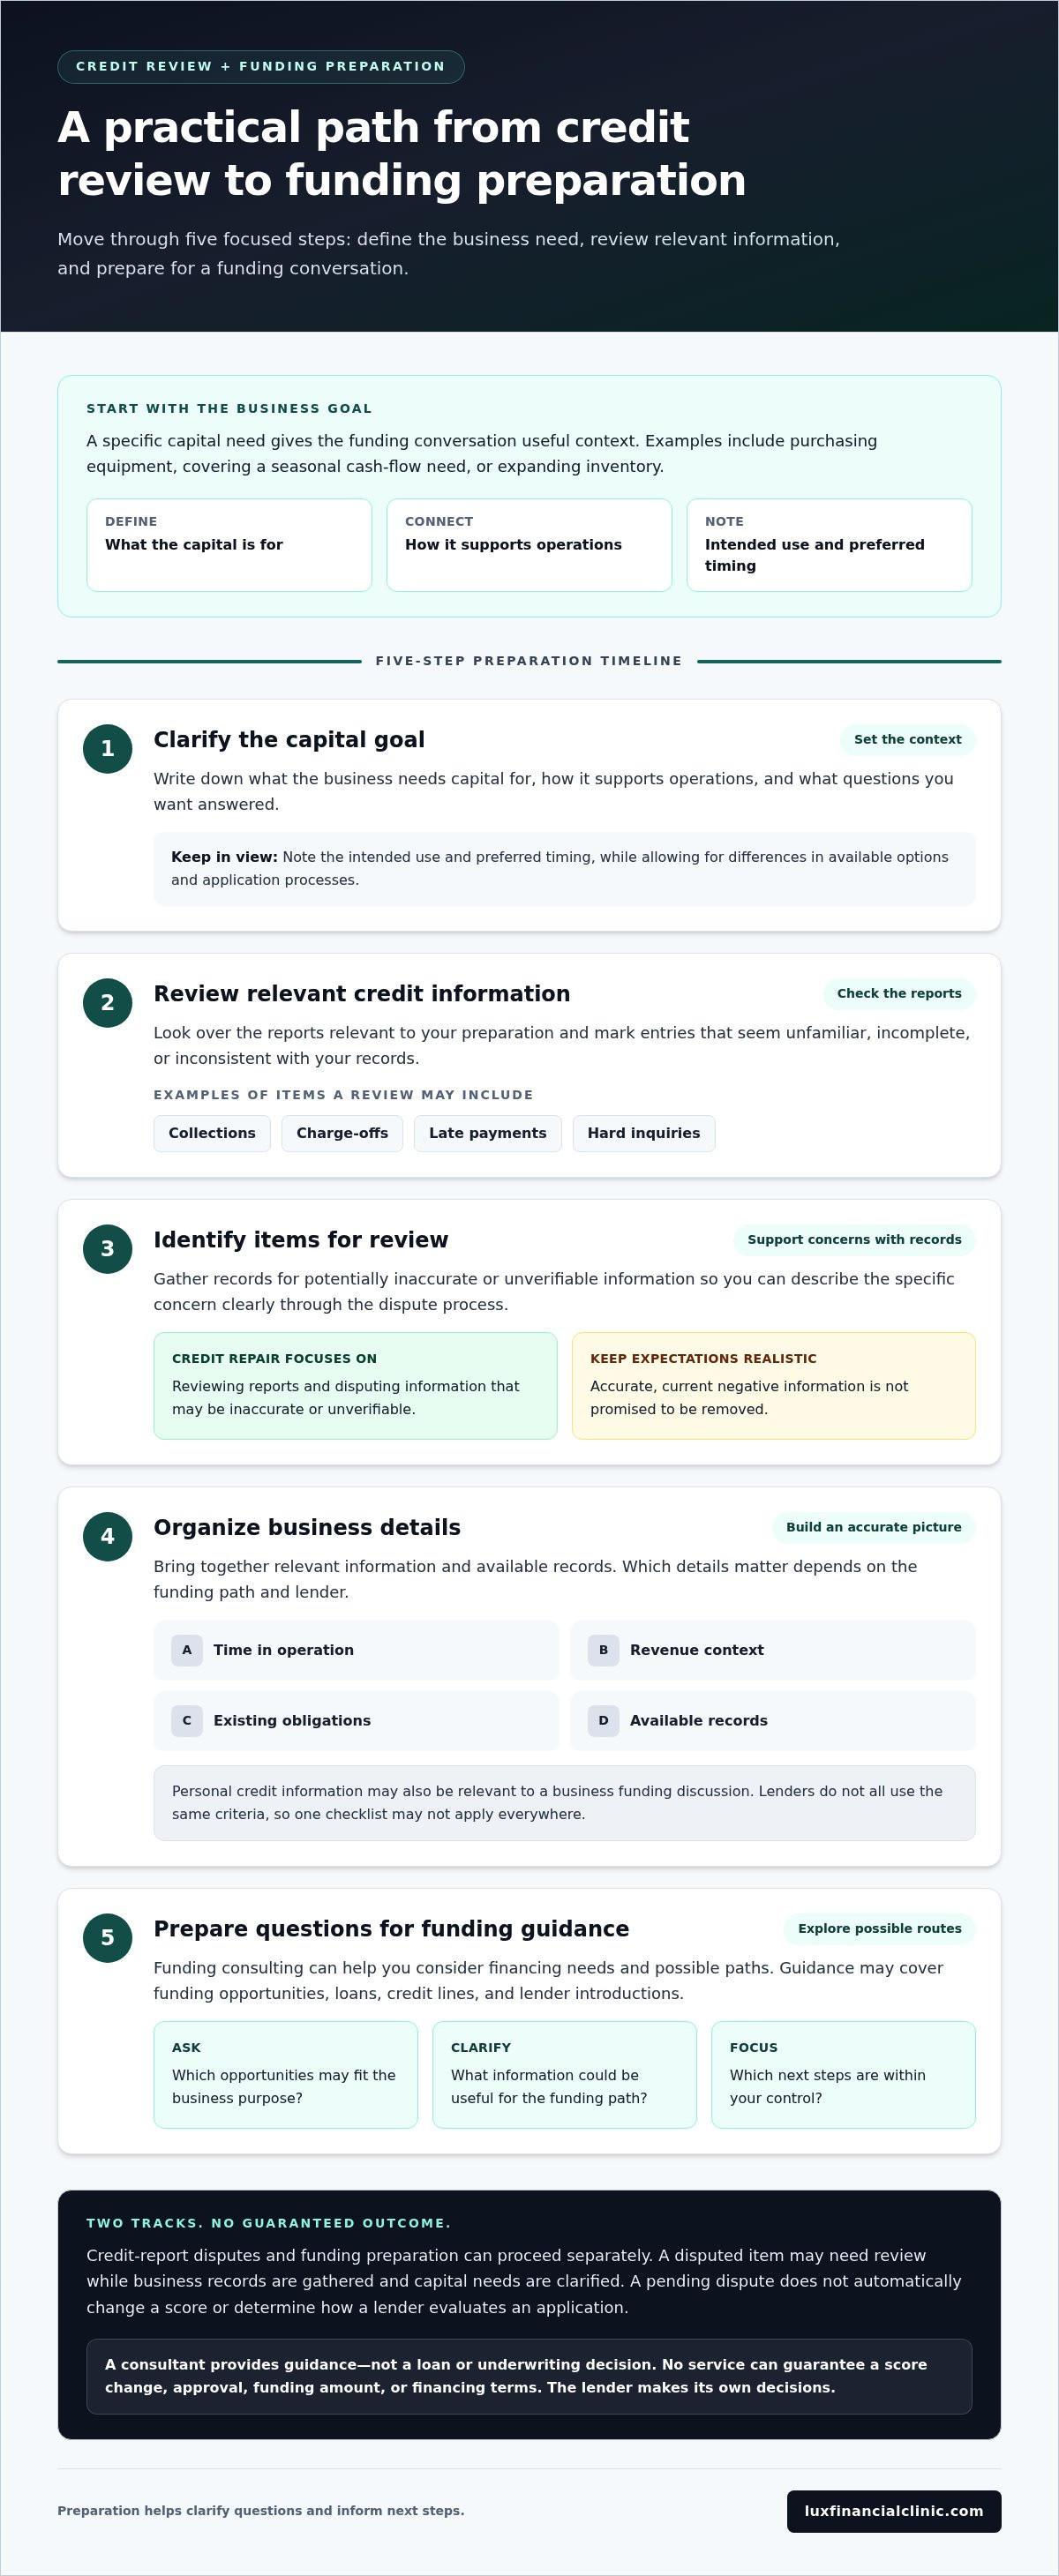
A practical sequence from credit review to funding preparation
Start by defining why the business needs capital. A specific goal, such as purchasing equipment, covering a seasonal cash-flow need, or expanding inventory, gives the funding conversation useful context. Note the intended use and preferred timing, while allowing for differences in available options and application processes.
- Clarify the goal. Write down what the business needs capital for, how it supports operations, and what questions you want answered.
- Review relevant credit information. Look over the reports relevant to your preparation and mark entries that seem unfamiliar, incomplete, or inconsistent with your records.
- Identify items for review. Gather supporting records for potentially inaccurate information so you can describe the concern clearly through the dispute process.
- Organize business details. Bring together information such as time in operation, revenue context, existing obligations, and available records. Which details matter depends on the funding path and lender.
- Prepare questions for funding guidance. Ask which opportunities may fit your purpose, what information could be useful, and which next steps are within your control.
Personal credit information may be relevant to a business funding discussion, while business records can help explain the company’s financial position. Lenders don’t all use the same criteria, so prepare an accurate picture of your circumstances rather than assuming one checklist applies everywhere. For an authoritative overview of government-backed options, the SBA Loan Programs page outlines loan programs for small businesses.
Why timing and expectations matter
Credit-report disputes and funding preparation can proceed on separate tracks. A disputed item may need review, while you gather business records and clarify capital needs. Lender processes also vary, so avoid planning around an assumed resolution date or treating a pending dispute as a change to your credit profile.
A dispute doesn’t automatically change a score or determine how a lender evaluates an application. Organized documents can make preparation more coherent, but they can’t control underwriting or guarantee approval, a funding amount, or specific terms. Their practical value is helping you understand questions, spot missing information, and make considered choices. For more on application preparation, the guide to qualifying for business loans offers related considerations.
Credit repair and funding consulting can complement one another without becoming a single promise or fixed sequence. If you want help identifying a starting point, a financial diagnostic consultation can bring your credit questions and business funding goals into one focused conversation.
Do You Need Credit Repair, Funding Consulting, or Both?
The right starting point depends on the question you need answered. Is something on your credit report potentially wrong, or are you trying to understand which funding paths might suit your business? You may need one service, both, or a clearer review of your circumstances before deciding. Combining services isn’t automatically necessary and doesn’t guarantee approval.
Primary need
Relevant service
Realistic next step
A report includes information that appears inaccurate or incomplete.
Credit repair
Review the report and gather records related to the entry.
You need to assess possible funding paths or prepare lender questions.
Funding consulting
Define the capital need and organize relevant business details.
You have report concerns and a business funding goal.
Both may be relevant
Address the report concern while organizing funding preparation.
When credit repair may be the first focus
If a report shows a negative entry you don’t recognize, or details that conflict with your records, begin with a careful review. Check the account information and relevant dates, then gather documents that may clarify the concern. This helps distinguish a potential error from accurate information before you decide whether a dispute is appropriate.
Credit repair doesn’t promise to remove accurate information. If you want to understand how dispute support works across credit bureaus, the three-bureau credit dispute services guide provides related context.
When funding consulting may add value
Funding consulting can help if you’re weighing funding paths, clarifying how much capital your business purpose calls for, or preparing questions for prospective lenders. You don’t need to identify a credit-report issue before organizing those questions. A focused conversation can help you outline what the business needs and what information to assemble, without suggesting that a particular option or outcome is assured.
Consider credit review and funding guidance together if you have both needs. For example, you may have spotted a potentially inaccurate report entry while preparing to explore capital for a defined business purpose. The work can be coordinated, but each service addresses a distinct concern and may proceed independently. Credit repair and funding consulting don’t make approval automatic; the lender remains responsible for its decision.
If you’re considering how these needs fit into a broader business-credit plan, explore small business credit consulting to learn more about organizing your next steps.
Prepare for Credit Repair and Funding Consulting With These Steps
A focused diagnostic conversation is easier when your records and goals are clear. You don’t need to have every answer in advance. A concise set of documents, questions, and known concerns can help distinguish what needs credit review from what belongs in funding preparation.
Before discussing credit repair and funding consulting, gather information relevant to your situation and keep sensitive details private. Don’t post account numbers, personal identifiers, or financial documents publicly. Share sensitive information only through appropriate private channels.
Gather information for a useful initial review
Use this checklist to organize what you already have. Bring what’s relevant to your circumstances rather than delaying a conversation while trying to assemble a perfect file.
- Current credit reports: Note the report date and mark entries you want reviewed. Separate clear discrepancies from items you’re unsure about, and keep related account records together.
- Business details: Write down the business’s basic structure, time in operation, current activity, and financial records you can readily access. Include existing business obligations that may be useful to discuss.
- Funding purpose: Describe what the capital would support, such as equipment, inventory, or working needs. Add your preferred timing and any known deadline without assuming a particular product or approval schedule.
- Questions and context: List what you want clarified, including which report entries may warrant review, which funding paths to explore, and what information to organize next.
Keep your observations factual. For a possible report error, record what appears inconsistent and what documentation you have. Label unresolved points as questions rather than confirmed errors. This makes it easier to discuss a considered next step.
Set a realistic definition of progress
Preparation can be productive even before a dispute is resolved or a funding path is selected. Useful signs of progress include more complete records, a clearly described concern for review, a considered dispute plan, and a better-organized list of funding questions. These steps add structure without predicting what a credit report will show or how a lender will respond.
Keep a simple record of open items: what you’ve gathered, what still needs clarification, and any timing constraints that affect your planning. If revolving capital is one possibility you’re weighing, the business line of credit readiness checklist can help you frame relevant preparation questions.
In brief: Current reports, business details, existing obligations, a defined funding purpose, timing notes, and clearly separated questions give a readiness discussion a focused foundation, while leaving outcomes open to review.
To bring your credit questions and business goals into one organized conversation, schedule a financial diagnostic consultation.
How Lux Financial Clinic Connects Credit Repair With Funding Guidance
Credit questions and business funding goals can sit side by side, but they call for distinct support. Lux Financial Clinic provides structured credit dispute support and business funding consulting as part of a broader planning conversation. Together, these services help you identify which needs are relevant and what steps may suit your circumstances. The purpose is clearer preparation, not a promised financing result.
What tailored support can include
Credit repair focuses on potentially inaccurate negative information in reports from major credit reporting bureaus. Dispute protocols can address collections, charge-offs, late payments, or hard inquiries when information appears inaccurate or cannot be verified. Reviewing the details first keeps the process centered on specific concerns rather than assuming every negative entry should be removed.
Lux Financial Clinic offers basic and comprehensive credit repair tiers. The comprehensive program includes a personalized credit-building roadmap and dedicated strategist support, connecting report review with longer-term credit-building guidance. A roadmap supports informed habits over time; it doesn’t promise a particular score change or removal of accurate information.
Funding consulting addresses a different question: how might your business approach its need for capital? Guidance can include exploring funding opportunities, loans, and credit lines, as well as lender introductions. The discussion is shaped around your goals and circumstances, including the business purpose for funds and the questions you want to resolve. Lux Financial Clinic provides consulting, not lending or loan underwriting. Lenders make their own decisions about applications and terms.
These services can be considered together when you have both a credit-report concern and a business funding goal. They can also be approached separately if only one need is pressing. A diagnostic conversation can help clarify priorities without implying that credit repair is required before discussing funding or that combining services creates a shortcut to approval.
Choose a considered next step
Before the conversation, identify the report entries you want reviewed, the business goal behind your funding plans, and the questions you hope to answer. From there, you can focus on a practical path: structured review of potentially inaccurate information, funding-opportunity guidance, or both where they fit your situation.
Keep expectations grounded. A consultation can support planning and help organize next steps, but it can’t guarantee score changes, removal of accurate information, lender approval, a funding amount, or specific financing terms. These boundaries help you make decisions with a clearer understanding of what each service can address.
If you’re ready to discuss your financial priorities and identify a thoughtful starting point, begin a financial diagnostic conversation with Lux Financial Clinic.
Take Your Next Step With Greater Clarity
Your next move doesn’t need to solve every financial question at once. Start by identifying what matters most now, whether that’s understanding a credit concern or shaping a funding plan. A focused conversation can turn uncertainty into priorities you can act on, while keeping expectations grounded in what you can prepare and what remains a lender’s decision.
With credit repair and funding consulting, Lux Financial Clinic offers structured dispute support across Experian, Equifax, and TransUnion, a personalized credit-building roadmap and dedicated strategist support through the comprehensive program, and funding guidance that can include lender introductions. These services support preparation, not promised score changes or financing outcomes.
Share your priorities and explore a considered path forward. Schedule a financial diagnostic consultation to begin with a clearer view of your options.
Frequently Asked Questions
Can credit repair and funding consulting help me get a business loan?
They can help you prepare to explore a business loan, but they can’t secure one for you. Credit repair may address report information that appears inaccurate, while consulting can help you frame the business purpose and understand possible funding paths. For example, if you’re considering equipment financing, organize how the equipment would support operations and the records that explain your business finances. A lender makes the approval decision.
Does credit repair guarantee business funding approval?
No. Credit repair can’t guarantee business funding approval, a particular score, or specific loan terms. A dispute may lead to a report correction if information is found inaccurate, but that doesn’t determine how a lender evaluates the full application. Treat credit review as one preparation step, not an assurance of financing. Keep business records current and make funding decisions based on your actual needs and available information.
Should I repair my credit before applying for business funding?
Not always. If you find a possible reporting error, reviewing it may be worthwhile, but there’s no universal sequence for every business or lender. You can organize business information and clarify your funding purpose while report concerns are being reviewed. If an application has a time-sensitive deadline, account for the fact that report review and lender processes may follow different schedules rather than assuming one will finish first.
What documents should I prepare for funding consulting?
Bring information that helps explain your business and why you’re considering capital. Useful items may include current credit reports, basic business details, revenue or cash-flow records, a summary of existing obligations, and a short description of how funds would be used. Requirements vary by funding path, so treat these as preparation materials, not a universal application list. Keep account credentials and sensitive identifiers private.
Can credit repair remove accurate negative information from my reports?
No service should promise to remove accurate negative information simply because it is unfavorable. For instance, a correctly reported late payment isn’t evidence of an error by itself. A review should focus on whether details such as the account, dates, or payment status appear inaccurate or incomplete. Keep records that support your concern, and distinguish a documented discrepancy from an item you’d simply prefer not to see.
Is funding consulting the same as getting a business loan?
No. Funding consulting is guidance, not a loan or lending decision. It can help you think through funding opportunities and prepare questions about options such as loans or credit lines. A lender, not a consultant, determines whether to approve an application and sets any applicable terms. Keep this distinction clear as you compare possibilities, so you know whether you’re seeking advice about a funding plan or applying for capital.
Can I use funding consulting if my personal credit needs work?
Yes. You can discuss business funding goals even if you have concerns about your personal credit. Bring a clear account of what you’re trying to fund and any credit questions you want to raise. Personal credit may be relevant to some funding reviews, but criteria differ. Consulting can help organize your questions and explore possible paths without treating a credit concern as an automatic disqualification or promising a lender’s response.


